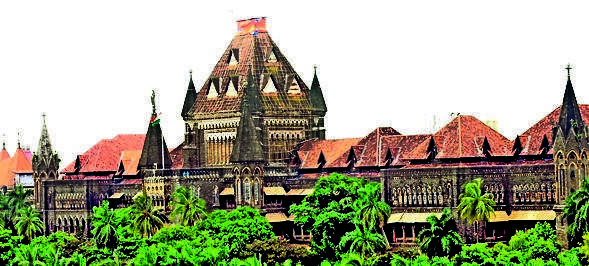
Mumbai: Bombay high court upheld a property tax demand made 13 years ago by a civic body on a public charitable trust that runs linguistic minority education institutions saying the trust is not providing free education and hence exemption cannot be granted.
The high court held that mere assertions that the trust is set up for a charitable purpose, runs a school and imparts education which is a charitable function, does not automatically become a ‘charitable purpose’ to invoke a legally provided property tax exemption.
“Any commercial activity, being carried out in the premises should therefore not enjoy the exemption and even if the activity of education is carried out with a profit-earning motive, it would then be denuded of the cover of ‘charitable purpose’ under Section 9 of the Maharashtra Public Trusts Act,’’ the high court observed after analysing the laws, the constitutional freedom to set up minority education institutions and the top court rulings.
The trust, Jai Hind Sindhu Education Trust, based in Pune, had challenged the property tax demand for 2012-13 by the municipal corporation of Pimpri-Chinchwad. The trust’s counsel, Dormaan Dalal, argued that property tax is exempt for charitable institutions, and it was solely imparting education at its premises, which is a charitable activity, thus entitling it to the tax exemption under Section 132 of the Maharashtra Municipal Corporations Act, 1949.
To claim an exemption, it is imperative to establish that the buildings and land or a portion of it are solely occupied and used for public charitable purpose, said the high court division bench of Justices Bharati Dangre and Manjusha Deshpande in a September 29 judgement, adding, “mere owning of land/building is not sufficient’’.
“That every educational institution achieves the charitable purpose, no longer is the accepted norm,’’ the bench observed. The high court said it disagreed with a “blanket proposition set out by the petitioners that education per se is a charitable purpose’’.
The high court agreed with municipal corporation’s counsel Srikrishna Ganbavale that a claim for exemption is not automatic, nor permanent. He had argued that the trust accepts fees and donations and does not provide free education.
State advocate general Milind Sathe said that academic institutions run with a profiteering motive, do not deserve protection. The AG said what has to be seen is whether the education income “is strictly used’’ to impart education, and, if otherwise, it can’t be labelled a ‘charitable purpose’ to rake in the exemption benefit that the law provides. The real test is to verify if an educational activity is for profit or only as a charitable purpose, he said.
“It is necessary to seek an exemption every financial year and there can be no exemption claimed in a wholesale manner,’’ the high court held and said the demand brooked no interference in the absence of the trust staking its claim on a year-to-year basis.
The trust said two of its institutions in Pimpri, Pune are government aided. While dismissing the petition, the court allowed the trust to “claim exemption for the years to come’,’ by applying with proper proof for case-by-case consideration.